Anthropic Is Borrowing $21 Billion to Buy Chips. That’s the AI Business Model Now
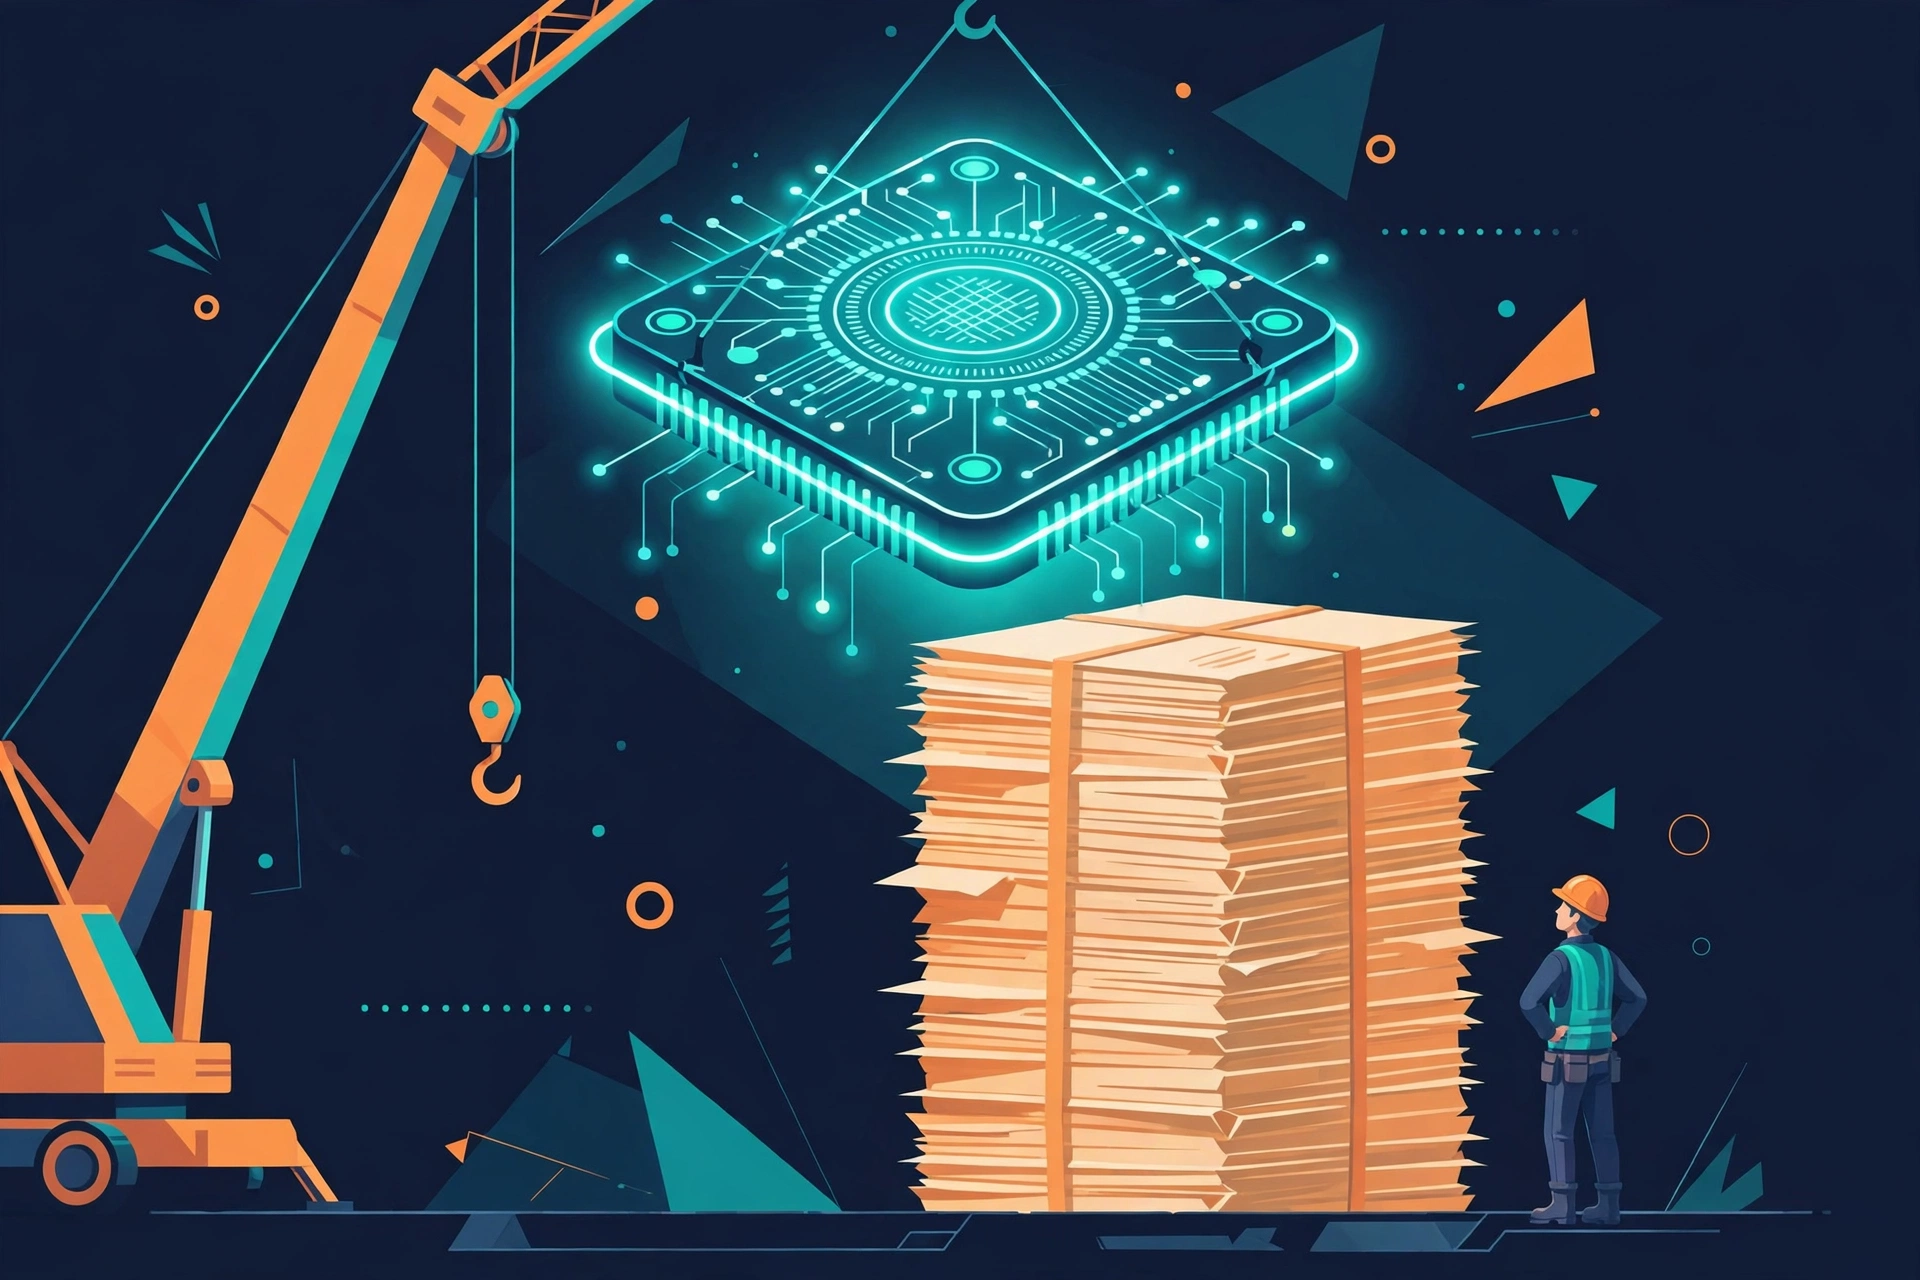
Anthropic did not just file for an IPO. It also, in the same week, became the clearest example yet of how frontier AI is actually paid for: not out of cash flow, not out of a single equity round, but out of a web of leases, loans, and vendor guarantees that turns computer chips into a financed asset.
The headline version is simple enough: banks are preparing to sell up to $21 billion of investment-grade bonds in early 2027 as part of a $63 billion financing package to supply Broadcom chips to Anthropic. The accurate version is more interesting — and more useful for anyone building with AI, because it shows what “compute” really costs when you are not a hyperscaler.
First, what the deal actually is
This is not Anthropic walking into a bank and borrowing $21 billion.
A newly created special purpose vehicle (SPV) buys Broadcom’s custom AI accelerators and networking equipment, then leases that equipment to Anthropic. Banks — Bank of America, Citigroup, and Morgan Stanley arranging the senior debt, with Blackstone as a committed second-lien lender — fund the vehicle. The lease payments from Anthropic service the debt. Up to $21 billion of the senior tranche is then expected to be refinanced in the bond market in five-year notes, depending on conditions.
The package finances about 1.7 gigawatts of AI computing capacity, with deliveries starting in 2027. It sits inside a larger, previously announced 3.5-gigawatt computing arrangement involving Broadcom, Google, and Anthropic.
So the $21 billion is the bond-market slice of a $63 billion lease machine. That distinction matters, because it is the whole story: in 2026, AI compute is increasingly something you rent through a financing structure, not something you buy with money you already made.
The twist: the chipmaker guarantees its own chips
Here is the part that made bankers, analysts, and skeptics all pay attention at once.
Broadcom is providing “residual value support” to the vehicle, equal to the first-lien financing — reported at roughly $42–43.5 billion, or about 69% of the total package. In plain English: the company selling the chips is promising lenders what those chips will be worth later, if Anthropic defaults or the equipment is worth less than expected.
That is why the deal cleared. It is also why it worries people.
On one side, it is rational vendor finance. Broadcom wants a long-term customer for its custom XPUs, Anthropic wants capacity without putting $63 billion on its own balance sheet, and lenders want a creditworthy backstop behind a fast-depreciating asset. On the other side, it creates a circular-looking loop: Broadcom sells the chip, guarantees its resale value to the lender, and — through separate convertible-note arrangements reported in its IPO filings — is also exposed to Anthropic as a lender of sorts. If utilization disappoints, Broadcom is exposed through more than one door at once.
This is not Broadcom’s first backstop for Anthropic either. An earlier $35 billion capacity expansion, financed with Apollo and Blackstone, carried Broadcom support reported at up to $29 billion. Stack the two together and Broadcom is standing behind something on the order of $72.5 billion of debt tied to one customer. Moody’s still rates Broadcom as one of the strongest large tech companies, according to reporting on the deal — but it has also warned that risk grows if deals like this stack up quickly.
None of that makes the deal fraudulent, or doomed. It makes it leveraged, interdependent, and very much of this moment.
Why now? Because the IPO filing made the math public
Anthropic filed its S-1 on October 26, 2026, to list Class A shares on Nasdaq under the ticker ANT. The filing is the context the financing needs:
- Revenue of $16.3 billion in the first half of 2026, up from $1.2 billion in the same period a year earlier.
- An operating loss of $693 million in that period, narrowed from $2.1 billion a year earlier.
- A headline net loss of $80.7 billion — but roughly $72.4 billion of that was a non-cash accounting charge from revaluing convertible notes as Anthropic’s valuation rose, not cash out the door.
- Nearly $9 billion in computing and infrastructure expenses in the first half alone, up from $2.3 billion a year earlier.
- More than 11,900 customers spending at least $100,000 a year, including about 250 spending $10 million or more.
In other words: real, fast-growing revenue, real enterprise demand — and compute costs growing just as fast. Anthropic also disclosed hundreds of billions in future purchase commitments. A company in that position does not finance growth out of last quarter’s profit. It finances it out of the future, and it asks the capital markets to believe that future arrives on schedule.
That is also why the timing matters for everyone else. Anthropic’s IPO is expected to be one of the largest ever. Its financing structures will become templates, whether they deserve to or not.
This is not just Anthropic. It is the whole AI economy in 2026
Zoom out and Anthropic looks less like an outlier than a leading indicator.
AI-related borrowing has already exceeded $455 billion globally in 2026, according to reporting on the Broadcom package, and other tallies put it at $466 billion through September, up from about $101 billion in the same period of 2025. JPMorgan Asset Management calculated that hyperscalers alone had issued $219 billion of investment-grade bonds in 2026, with their spreads widening about 30 basis points year to date, against 2 basis points for the broader dollar investment-grade index. Hyperscalers’ share of dollar investment-grade issuance was set to rise to 9% this year, from 2% in 2022–2024.
The pattern repeats across the industry: Nvidia investing $3 billion in Meta as part of a deal that gets Meta more Nvidia hardware; SpaceX signing a roughly $40 billion equipment-finance lease with Apollo; Oracle tied to $133 billion of debt in one JPMorgan tally as it scales cloud capacity for a $300 billion OpenAI contract.
The old model was: build a product, sell it, reinvest the profit. The new model, at frontier scale, is: sign a multi-year compute commitment, finance the hardware through a vehicle, lease it back, and hope revenue grows into the payment schedule before the hardware becomes obsolete.
That can work. It is also exactly how capital-intensive booms have always worked — railroads, telecoms, airlines — and how they have sometimes failed.
The dot-com comparison is lazy. The question behind it is not
Every article about AI debt now gets the same pushback: “This is not the dot-com bubble, because these companies have real revenue.” That is true, and it misses the point.
The dot-com companies that failed did not fail because nobody used the internet. They failed because they financed long-lived infrastructure with short-lived assumptions about how fast revenue would arrive, and because vendors financed their own customers to keep the orders flowing.
Anthropic has real revenue. So do Meta, Microsoft, Alphabet, and Oracle. The question is not whether AI is real. The question is whether the financing assumes a growth rate, a utilization rate, and a chip lifespan that all hold at the same time.
Three things have to stay true for deals like this to look smart in hindsight:
- Utilization stays high. Leased capacity that sits idle still has a lease payment. Anthropic’s own disclosures say its consumption of the new capacity depends on its continued commercial success.
- Chips hold value long enough. Residual value support is a bet on what used AI accelerators will be worth in a few years — from the same company selling the newer chips that make older ones obsolete.
- Revenue grows into the schedule. Anthropic’s H1 2026 compute bill was nearly $9 billion. Its future commitments run into the hundreds of billions. The gap between those two numbers is the bet.
If all three hold, this is just infrastructure finance, boring and profitable. If any one breaks, the structure amplifies the break — because the debt, the lease, and the vendor guarantee are all tied to the same underlying demand.
What this means if you are building with AI, not financing it
You are probably not about to sign a $63 billion chip lease. The lesson still applies, at your scale, because the same forces are reshaping the tools you rent:
- Rent compute, don’t worship it. The frontier labs are leasing, not owning, for a reason: flexibility beats ownership when hardware turns over every 18–24 months. For a small builder, that means multi-model, multi-provider setups beat a single-vendor bet, even when the single vendor offers the best demo today.
- Measure utilization before you scale capacity. Anthropic’s risk is idle gigawatts. Yours is idle subscriptions, unused API tiers, and agents running on every ticket whether they help or not. Before you buy more capacity, find the work that is actually using it — and kill the work that is not.
- Watch who guarantees whom. When a vendor offers you generous financing, credits, or “free” capacity, ask what it needs from you in return: exclusivity, volume commitments, data, or a public logo. Vendor finance is never free. It is a bet that you will still be a customer when the bill comes due.
- Price in the refinancing. The $21 billion bond sale is not happening today; it is planned for early 2027, “depending on conditions.” That phrase should be familiar to anyone who has ever renewed a lease in a bad market. If your AI stack depends on a price, a credit, or a rate that resets next year, plan for the reset, not just the introductory offer.
- Don’t copy the financing, copy the discipline. Anthropic’s filing shows a company narrowing its operating loss while revenue grew 14-fold year over year. That is the part worth imitating: revenue per unit of compute, customers who actually pay, and a clear-eyed view of what each new capability costs to run.
The bottom line
Anthropic borrowing $21 billion to buy chips — through a $63 billion lease vehicle, backstopped by the chipmaker itself — is not a scandal, and it is not a proof of a bubble. It is the AI business model, stated plainly: enormous, lumpy, front-loaded compute costs, financed against a future in which demand keeps growing fast enough to pay for them.
For builders, the takeaway is not to fear that model or to copy it. It is to understand it, because it determines the price, availability, and terms of the tools you will be offered next. The companies that win in the agentic economy will not be the ones with the most chips. They will be the ones who know, to the dollar, what each unit of intelligence is worth — and who refuse to pay for more of it than the work actually needs.
Sources (checked October 28, 2026): Broadcom / Bank of America / Blackstone / Citi / Morgan Stanley announcement of the $63 billion financing structure, via Investopedia and The Crypto Basic reporting, October 27, 2026. Bloomberg reporting on the planned up to $21 billion bond sale in early 2027, via The Private Banker, October 28, 2026. Anthropic S-1 filing, October 26, 2026, via TechCrunch and The Wrap: $16.3 billion H1 2026 revenue, $693 million operating loss, $80.7 billion net loss including ~$72.4 billion non-cash convertible-note charge, ~$9 billion H1 compute and infrastructure expense. JPMorgan Asset Management hyperscaler bond figures and AI borrowing totals ($455–466 billion in 2026), via The Private Banker, Barron’s, and Coinpaper reporting. Earlier $35 billion Anthropic capacity deal and Broadcom backstop figures, via TheStreet / Reuters reporting.
This article is analysis for builders and operators, not investment advice. Financing terms are as reported at publication and may change as the bond sale and lease deliveries proceed.